01
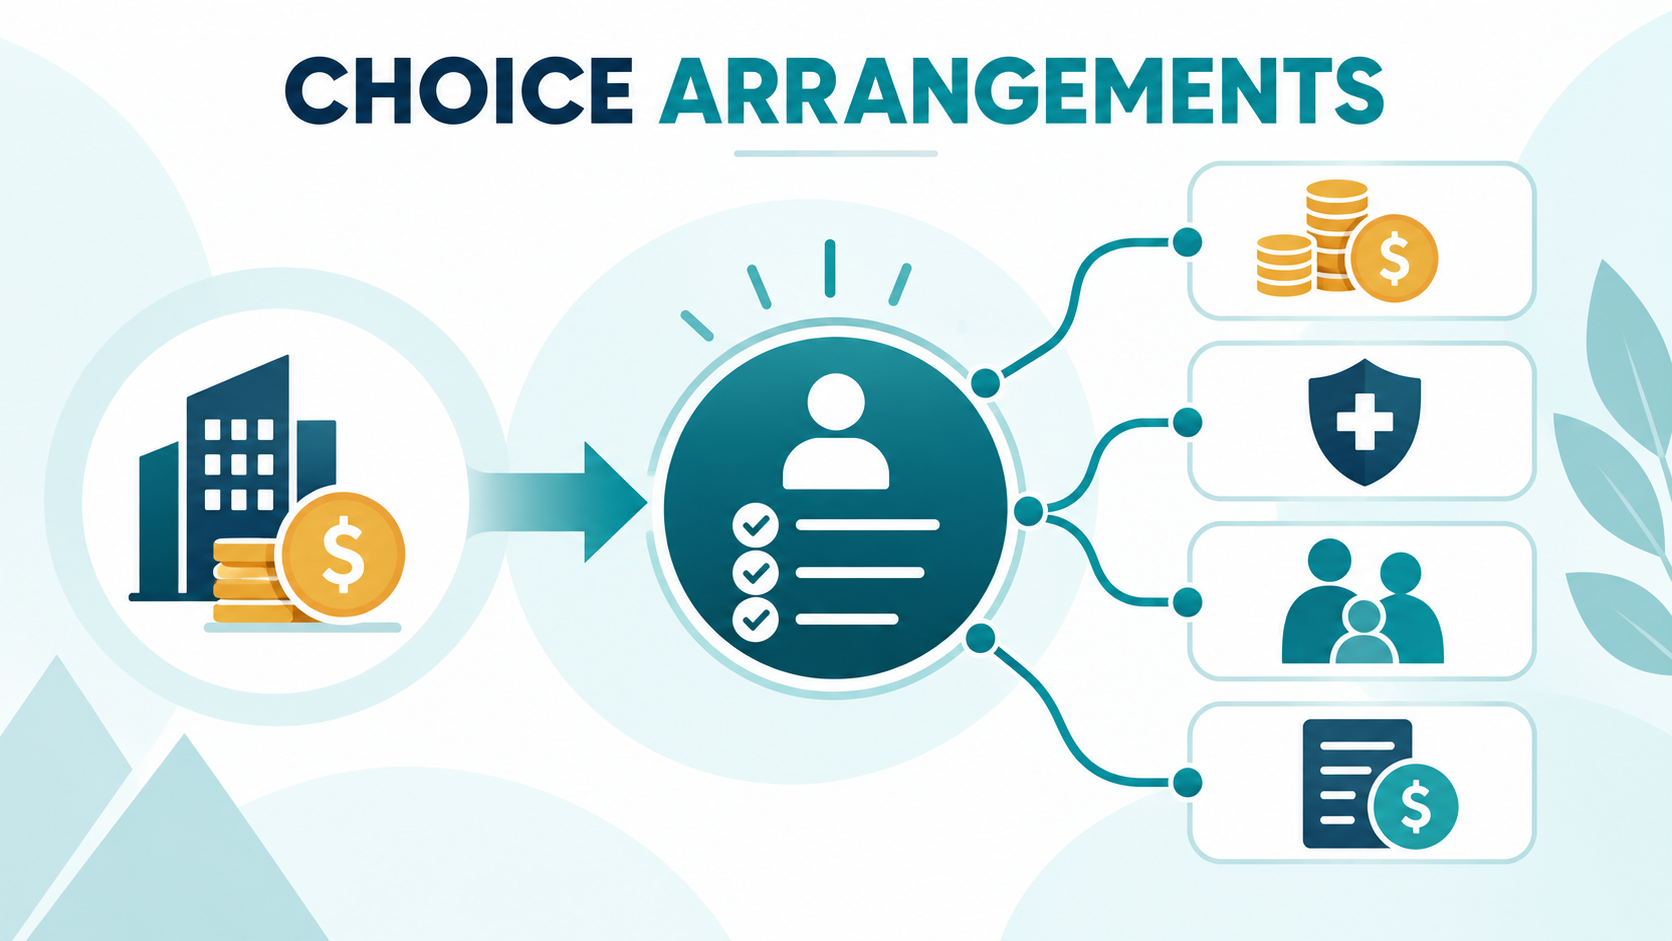
Employer sets the budget
The employer defines eligible classes and tax-advantaged contribution amounts.
 CHOICE ARRANGEMENT EXPERTS
CHOICE Arrangement is the new public-facing term for ICHRA. The governing rules, plan documents and reporting may still use Individual Coverage HRA or ICHRA.
CMS and SBA now use CHOICE Arrangements in public-facing employer resources. The governing rules and many compliance materials still use “individual coverage HRA” or “ICHRA,” so The ICHRA Shop uses both terms during the transition.
The employer defines eligible classes and tax-advantaged contribution amounts.
Employees select individual coverage based on doctors, prescriptions, household needs and budget.
The right platform handles eligibility, substantiation, reimbursements and ongoing service.
The ICHRA Shop was the first to dive fully into independent ICHRA consulting in February 2020—just after employers could begin offering the arrangement. Six years later, we remain category leaders, helping employers and brokers turn a new idea into a practical, measurable benefits strategy.
We do not start with a vendor. We determine how the employer should finance healthcare—then select the right partners to carry out the strategy.
Not as a matter of governing law. CHOICE Arrangement is the newer public-facing term; federal rules, plan documents, disclosures and reporting may still use Individual Coverage HRA or ICHRA.
No. Results depend on geography, workforce, carrier availability, contributions, affordability and administration. We compare the real alternatives.
Brokers should not have to research and interview more than 40 ICHRA vendors to find the right fit. We do that work for them. The ICHRA Shop independently analyzes the employer’s workforce, markets, contribution strategy, service needs and—when requested—risk intelligence. We then recommend the best-fit vendor or combination of partners, support implementation and enrollment, and protect the broker’s client relationship.
Start with independent cost, market and risk analysis.